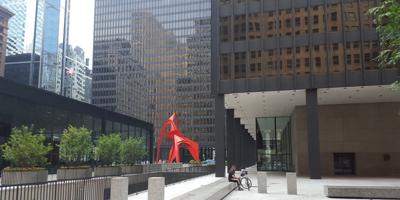


Dirksen Federal Courthouse, Chicago
CHICAGO — A federal judge has temporarily paused Illinois from enforcing restrictions against Kalshi and Coinbase for "predictive" activities related to sports wagering.
In her decision, U.S. District Judge Martha Pacold explained the state, through Attorney General Kwame Raoul, sent Kalshi a cease-and-desist letter with respects to its online prediction markets for sports contests. The state also targeted Coinbase for its role in offering virtual wallets so Kalshi users can trade with cryptocurrency, implying both companies violated the Illinois Sports Wagering Act.
Using examples like the World Cup final or LeBron James signing a free agent contract, Pacold explained Kalshi doesn’t set betting lines like a conventional sports book, but prices for prediction contracts “reflect those at which users buy and sell” those contracts, which also enables users to “bet on bets” by selling contracts they feel are overvalued before an event settles.
Coinbase sued the state, seeking to head off the state’s legal threats. After Pacold conducted oral arguments, the General Assembly enacted its fiscal 2027 budget and other legislation that included new transaction fees on exchange wagers, which lawmakers defined as “an agreement, contract, transaction or swap that is offered, traded or executed on a prediction market or exchange tied to a sporting contest or sporting event.”
Pacold cited a “nationwide wave of litigation” as states sought to regulate Kalshi contracts and noted the federal government sued Illinois as did Kalshi and the Commodity Futures Trading Commission. Because all the parties opted to stand on their briefs, Pacold didn’t conduct another session of oral arguments. Further, since “the plaintiffs advance similar positions, and the defendants are shared,” she resolved all the litigation in her Oct. 2 opinion, noting the relevance of the Commodity Exchange Act.
Although that federal law gives the CFTC significant exclusive authority, she explained, other federal agencies, state governments and native tribal groups share certain powers. “Swaps” fall only under the CFTC, she explained, adding the definition of that term is central to the ongoing dispute.
“This case mostly turns on the clause of the swap definition that includes contracts ‘dependent on the occurrence, nonoccurrence, or the extent of the occurrence of an event or contingency associated with a potential financial, economic, or commercial consequence,” Pacold wrote. “The term ‘swaps’ and its definition were added in 2010. The addition was included in a broader reform following the subprime mortgage crisis and subsequent recession.”
She further referenced credit default swaps, which paid when borrowers defaulted, noting those incidences outpaced market expectations causing problems for investors that spread throughout the market. Subsequent reforms predated Kalshi, Pacold noted, but not the CFTC’s recognition of event contracts, which dated to the 1992 presidential election and a University of Iowa futures market.
Since the U.S. Seventh Circuit Court of Appeals — in 2019’s Effex Capital v. National Futures Association — already held the Commodity Trade Act doesn’t expressly pre-empt state laws, Pacold explained, she needed only to consider whether the ISWA was in conflict.
Pacold rejected arguments that differentiated “between the results of games and the contingencies associated with those results,” such as a bet on whether the Cubs would win a game or a prediction contract on the team’s specific record after that game concluded, as “basically semantics.” She noted that some predictions, such as the actual length of a best-of-seven series, are legally consequential and have significant financial implications outside the wins and losses, while others, like the color of Gatorade poured on a winning coach, are not.
“The statute, as interpreted here, does not federalize all gambling, or even all sports gambling,” Pacold wrote. “Instead, the statute governs gambling so far as it takes the form of swaps. … People may view these contracts as gambling, but little in the statutory definition turns on what people think. Instead, most of the definition turns on commercial function.”
She further delineated between gambling and the use of swaps as a potential insulator against financial loss, such as if farmers could “buy weather swaps to hedge against the risk of a bad season,” while also noting “sports bets fit the Commodity Exchange Act better than sometimes assumed” because the law gives the CFTC discretion to ban gaming contracts.
“When the CFTC gained ‘exclusive jurisdiction’ over ‘swaps’ in 2010, Kalshi did not exist,” Pacold wrote. “Most sports bets were wagers placed in a sportsbook instead of traded on a designated contract market. Since then, swaps and designated contract markets have become the site of sports betting. But the meaning of words enacted in 2010 does not turn on the behavior of companies like Kalshi — or even technological “development.”
Returning to Effex Capital, as well as a 1992 Seventh Circuit opinion regarding the Chicago Board of Trade, Pacold said a state law is pre-empted if it impacts contract trading. She further explained Raoul’s threat to invoke the law’s requirement for a license and its terms clearly represents impermissible controls of Kalshi’s swap sales, while “others raise further questions,” such as the flat and percentage-based fees on wagers.
“Illinois attempts to regulate how Kalshi’s swaps can be structured and what sorts of sporting events they can relate to,” Pacold wrote. “Illinois also attempts to control whom Kalshi can allow to buy and sell swaps with age limits and geographical restrictions. Compliance would accordingly force Kalshi to build a market solely for Illinoisans — all at the threat of criminal penalties, against Kalshi itself, for non-compliance.”
The state argued current CTFC regulations mean Kalshi’s contracts are illegally listed, meaning its own law can’t be found in conflict. While Pacold conceded some contracts may be listed improperly, she still said the state law “regulates what the CFTC can and cannot permit designated contract markets to do,” subjecting companies like Kalshi to uneven regulation.
As to fees, Pacold said she was expressing only preliminary views because the parties hadn’t fully explored the issue. But courts have treated regulation different from costs, she explained, and said Illinois “taking a cut of Kalshi and Coinbase’s profits, without more, might not pose the same conflict as regulating an entire market.”
In agreeing to grant the preliminary injunction, Pacold said allowing Illinois to enforce its law would inflict “irreparable harm” in the form of potential civil and criminal penalties, as well as a downstream inability to sue the state for damages on account of sovereign immunity or the challenges in calculating potential profit loss.
Illinois also argued against the injunction by noting Coinbase waited “to file this lawsuit at the last minute and demand instant relief” despite knowing about the law for months, then noted Kalshi and the federal government waited even longer. But Pacold said Coinbase lacked standing before partnering with Kalshi and she noted Kalshi and the government challenged the transaction fee in the same month it was enacted.
Finally, Pacold said, the “plaintiffs are likely to succeed in demonstrating that several of Illinois’ laws are pre-empted. Neither Illinois nor the public has much interest in enforcing laws” likely to be nullified, the judge said.
