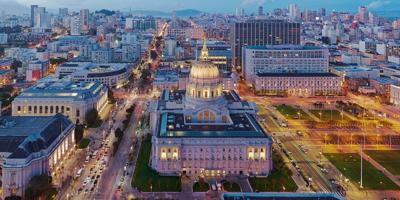


San Francisco City Hall
SAN FRANCISCO — A state appeals panel won’t let San Francisco enforce the voter-approved Empty Home Tax, saying California law forbids cities from effectively forcing housing owners to either rent out homes or apartments they own or face large punitive taxes.
The Sept. 11 ruling marks the latest development in a legal battle that dates to 2022, when 54.5% of voters approved Proposition M, codifying in the city’s Business Tax and Regulations Code an additional tax on apartment and other potential rental housing spaces that go unoccupied for at least 182 days of the preceding calendar year. The tax would apply to any “house, apartment, mobile home, group of homes, or a single room that is designed as separate living quarters,” in which people “live and eat separately from any other persons in the building and which have a kitchen and direct access from the outside of the building or through a common hall.”
Named plaintiffs Eric and Andrew Debbane, Robert Friedland, Natasa Zec, San Francisco Apartment Association, Small Property Owners of San Francisco Institute and San Francisco Association of Realtors sued in February 2023.
In November 2024, San Francisco County Superior Court Judge Ronald E. Quidachay declared the tax amounts to an unconstitutional taking of property and further trespasses on property owners’ rights to allow family to live in apartments or keep certain units empty, rather than leasing to strangers. He further agreed the tax violates California constitution privacy rights by forcing people to “share the property on which they reside with others, against their will,” or face what amounts to a costly annual financial penalty.
Quidachay’s written ruling followed nearly a month after a different judge, Charles Haines, indicated during an Oct. 31 that he would strike down the tax as unconstitutional under both the U.S. and California constitutions and under California's state Ellis Act, which empowers landlords to evict tenants and pull properties off the market without selling the property. Quidachay’s written order indicated he signed the order on behalf of Haines.
The plaintiffs challenged the ruling before the California First District Appellate Court. Justice Kathleen Banke wrote the panel’s opinion; Justices Monique Langhorne Wilson and Charles Smiley concurred. While the appeal was pending, the San Francisco Board of Supervisors passed an ordinance suspending the tax pending the final courtroom outcome.
Had the law taken effect, the tax would’ve been first charged in 2025 and then escalate for each year officials determine a dwelling remains unoccupied. The amounts charged were to begin at $2,500 for a dwelling unit of less than 1,000 square feet; $3,500 for a unit between 1,000-2,000 square feet; and $5,000 for units measuring more than 2,000 square feet.
On appeal, San Francisco argued its home rule powers allow it to enact a local tax measure. Banke explained the panel didn’t need to decide whether, as the plaintiffs argued, Proposition M was instead a financial penalty mechanism, noting the underlying reality that local laws concerning local affairs are not inherently insulated “from conflicting directives of state law.”
The panel further quoted the Ellis Act’s provision holding no local ordinance can “compel the owner of any residential real property to offer, or to continue to offer, accommodations in the property for rent or lease,” then detailed the legal history of decisions defeating local ordinances found to “place conditions on a residential property owner’s right to not offer their property for rent are preempted if those conditions are not required by the Ellis Act.”
The city argued Proposition M is different because it focuses on bringing in or returning units to the rental market while all the other matters addressed when a landlord seeks to exit the market. But the panel said the Ellis Act protects both sides of the coin and said “there is no material difference” to wanting to exit the market or wanting to stay out.
“Otherwise, as the city apparently sees it, while a property owner, indeed, has the right to exit the residential rental business, they have no correlative right to remain out of that business and can be pressured back into it on pain of significant taxation,” Banke wrote. “This circularity in reasoning is a patently unreasonable reading of the Ellis Act.”
The panel further rejected the city’s arguments about property owners’ options for avoiding the tax. It said the government forfeited one — that owners use their space for something like a personal gym or art studio — by not bringing it up during the initial trial. Even so, Banke noted, the notion doesn’t square with the word “unused” in the ordinance and ballot language, noting Proposition M proponents sought to target “wealthy individuals who purchase units but don’t use them” and the clear implication the tax was intended to apply to a residential space being somehow kept off the housing market.
“There is not the slightest suggestion in either the language of Proposition M — or the report that preceded it, or the voter materials for and against it — that the Empty Homes Tax does not apply to the owner of a residential property who chooses not to reside thereon if, for example, they festoon the walls of their property with personal photographs and call it their personal photo gallery, or roll out a yoga mat on the living room floor and pronounce the property a personal workout studio,” Banke wrote. “To the contrary, such a construction is squarely at odds with the intent of the proposition — to require owners of residential properties, on pain of significant taxation, to put such properties to residential use and keep them in such use.”
Banke also said the city’s own planning code already indicates the principal permitted use of dwelling units is for residential use and accessory use is limited to when “the principal use of the residence remains as a dwelling.”
The city’s other option for avoiding the tax includes moving into any “vacant” property, which the panel called a sleight of hand because “there is no issue as to residential property owners who reside on their residential property,” while also agreeing the potential financial penalties put a “prohibitive price” on exercising Ellis Act rights.
After agreeing the Ellis Act does conflict with Proposition M, the panel then looked at the other factors determining whether the state law should be allowed to pre-empt the local ordinance.
“Notably, the city makes no argument that these additional factors are not present, and we readily conclude that they are,” Banke wrote. “The Legislature intended to prevent owners from being compelled to rent their residential property by the actions of public entities. Thus, the Ellis Act both addresses a matter of ‘statewide concern’ and is reasonably related to the resolution of that concern.”
The panel further noted the Ellis Act is “narrowly tailored” insofar as it doesn’t address a government’s legal power to enforce residential rental contracts or regulate land use through planning or zoning, among other issues.
Because the Ellis Act pre-empts Proposition M, the panel affirmed the superior court ruling and didn’t consider any additional arguments, including anything constitutional. It also ruled the plaintiffs are entitled to the costs of their appeal.
Nielsen Marksamer represents the plaintiffs.
The government is represented by the office of City Attorney Thomas Lakritz.
The Pacific Legal Foundation and Berkeley Property Owners Association filed in support of Debanne.