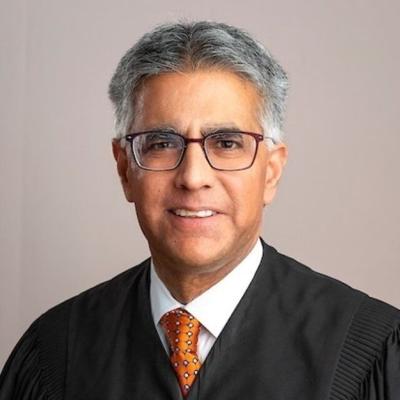
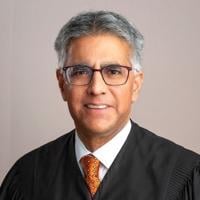


Illinois First District Appellate Justice Sanjay Tailor has been appointed to serve on the Illinois Supreme Court, effective Jan. 30, 2026.
SPRINGFIELD — All mortgage liens in Illinois last 20 years, meaning some can even survive a decade after the lienholders run out of time to sue to collect outstanding debts, the Illinois Supreme Court has ruled.
Justice Sanjay Tailor wrote the 7-0 opinion, filed Sept. 24, resolving a dispute between Sara Watkin and the Chicago Title Land Trust Company.
According to court records, the case dates to June 24, 2011, when Marline and Melvin Stein, the beneficial owners of a Wilmette property held in trust with Chicago Title, executed a note in favor of Watkin, as trustee of a revocable trust in her name, in which the Steins would pay Watkin up to $150,000 on a one-year, interest-bearing note. The Steins never made a payment.
On June 23, 2022, a day before the 10-year limitations windows on the note and the mortgage would lapse, Watkin filed a foreclosure on the property. Chicago Title moved to dismiss, arguing Watkin either failed to send an acceleration note or to provide evidence of doing so. A circuit court judge dismissed the claim, and Watkin didn’t amend the pleading.
On June 26, 2023, Chicago Title filed a complaint to quiet title. It eventually filed a second amended version of that complaint, asking the court to order Watkin’s mortgage line was null owing to a failure to file anything before the 10-year limitations window expired and preventing Watkin “from asserting any estate, title or interest in the subject property.”
Watkin responded by requesting summary judgment, arguing that although it was too late to reopen or refile the foreclosure, that timeline didn’t impact the validity of the lien.
“The expiration of the statute of limitations period does not extinguish the underlying debt” under state law, Watkin said, meaning she still had “the right to appeal to the debtor to honor the best out of a sense of moral obligation even if the legal obligation” was no longer enforceable. As such, she contended, Chicago Title’s claim to an unencumbered title didn’t trump her lien.
A Cook County Circuit Court judge agreed with Watkin and granted summary judgment, then an Illinois First District Appellate Court panel affirmed.
“The statutes say nothing about the extinguishment or continuing existence of the mortgage lien,” Tailor wrote, but a relevant civil procedure code section “expressly provides for the termination of mortgage lines, stating that ‘the lien of every mortgage, the due date of which is stated upon the face, or ascertainable from the written terms thereof, shall cease by limitation after the expiration of 20 years from the time the last payment on such mortgage became or becomes due’ unless the owner of the mortgage lien files an extension agreement showing that the time for payment of the indebtedness has been extended.”
Chicago Title pointed to the court’s 1878 opinion, Emory v. Keighan, which held “when the debt is paid, discharged, released or barred by the Statute of Limitations, or by a judgment of a court, the mortgage is gone, and has effect no longer.” But that ruling, and other similar cases Chicago Title cited, “were decided well before” the General Assembly in 1941 enacted the section of the Limitations Act that set the life of a mortgage lien, Tailor wrote. That law, like the relevant civil code passage, “extinguished a mortgage lien 20 years after the last payment became due.”
Chicago Title argued the sole purpose of the code passage was clearing stale mortgages from the public record and, Tailor wrote, “is designed exclusively to protect third-party purchasers and encumbrancers by requiring the parties to the mortgage to record their mortgage lien extension agreements.”
The court, however, focused on the word “every” and said lawmakers could have clarified if they intended the 20-year window to apply only in certain situations. The justices noted states like Oklahoma, Colorado, California, Montana and Washington have laws endorsing Chicago Title’s position — a lien extinguishes or quiet title actions are authorized when a foreclosure is time barred — and the absence of similar language in Illinois statutes is telling.
“Our conclusion is further supported by the purpose behind a statute of limitations,” Tailor wrote, noting those limits affect remedies but don’t “extinguish substantive rights.” As such, the debt remains.
“Chicago Title brought a quiet title action in its capacity as trustee, seeking to remove Watkin’s mortgage lien from title to the Wilmette property even though the trust beneficiary Marline never paid her debt to Watkin,” Tailor wrote. “Equitable principles do not support granting Chicago Title the relief it seeks. …
“If Marline wishes to remove Watkin’s mortgage lien from the Wilmette property before it becomes extinguished by operation of law,” Tailor concluded, “she can secure the lien’s release by satisfying her debt to Watkin. Otherwise, she will have to wait.”