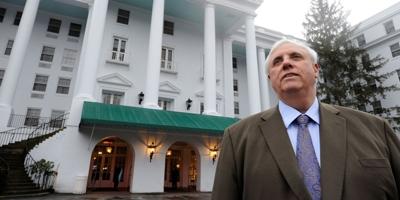


Jim Justice outside The Greenbrier
BECKLEY – A federal judge has ruled against The Greenbrier, the historic resort associated with U.S. Sen. Jim Justice and his family, in a dispute over more than $52 million owed on a pandemic-era loan.
Judge Frank Volk’s November 18 memorandum opinion and order grants First Guaranty Bank’s summary judgment on its breach of contract claim and dismisses The Greenbrier’s counterclaim seeking more than $50 million in damages. The court rejected the company’s argument that First Guaranty acted in bad faith by refusing to change the loan’s repayment terms.
The ruling comes three months after the Justice family completed a roughly $500 million joint venture that gave Kennedy Lewis Investment Management a controlling interest in The Greenbrier. That transaction helped resolve separate debt litigation but did not end First Guaranty’s case against the hotel company.
First Guaranty sought $52,379,817.04 in principal, interest and late fees calculated through August 19, plus continuing interest and collection expenses.
First Guaranty originally filed its lawsuit in federal court in Louisiana in July 2024. The case was transferred to the Southern District of West Virginia in November 2025 after The Greenbrier sought a change of venue. Huntington businessman Marshall Reynolds is chairman of the board for First Guaranty.
The dispute involves a $35 million loan First Guaranty made to The Greenbrier on December 22, 2020, through the Federal Reserve’s Main Street Lending Program, authorized under the Coronavirus Aid, Relief and Economic Security Act. According to the opinion, The Greenbrier did not dispute that it failed to meet the loan’s repayment requirements.
Instead, The Greenbrier argued the bank violated its duty of good faith and fair dealing by declining a February 2025 proposal that would have allowed the company to repay the outstanding principal by Dec. 31, 2026. The court found nothing in the loan documents required First Guaranty to accept that proposal.
“Greenbrier does not direct the court to the contractual or bargained-for source of this purported obligation,” the opinion states. “Indeed, at no point does Greenbrier assert FGB owed any such duty under the Note’s terms, nor does a review of the loan documents provide as much.”
Under the original repayment schedule, The Greenbrier was required to make monthly interest payments beginning in January 2022, followed by principal installments in December 2023 and December 2024. The remaining balance was due Dec. 22, 2025.
The Greenbrier defaulted when it failed to make the first principal installment on Dec. 22, 2023. Before then, most of its interest payments had been late, according to the opinion. The company stopped making payments altogether after April 2024.
As of Aug. 19, the outstanding balance included approximately $35.36 million in principal, $17.01 million in accrued interest and $4,500 in late fees. The opinion lists a default interest rate of 21% annually, or approximately $20,627 per day. First Guaranty also sought attorney fees, costs and related enforcement expenses under the loan documents.
The Greenbrier contended its proposed extension could have reduced its liability or eliminated the need for litigation. It also questioned whether First Guaranty had adequately pursued approval from the Federal Reserve, noting the bank had not received a written rejection.
The bank’s chief executive testified that Federal Reserve officials ultimately rejected the proposal during telephone discussions, according to the opinion. But the court’s ruling turned on whether First Guaranty had a contractual duty to modify the loan, not whether the rejection had been put in writing.
Applying Louisiana law, as required by the promissory note, the court concluded that a claim of bad-faith performance must rest on an underlying contractual obligation. It also rejected The Greenbrier’s contention that the bank failed to mitigate its damages by declining the proposed extension.
“Mitigation does not require the non-breaching party to cure that breach once it has occurred,” the opinion states.
Court rejects counterclaim
The Greenbrier’s counterclaim centered on a “negative pledge” provision attached to the promissory note. Subject to specified exceptions, that provision restricted the company’s ability to pledge its property, assets or revenue as security for other borrowing while the loan remained outstanding.
The Greenbrier alleged the provision had been included by mistake and that First Guaranty’s refusal to remove it damaged existing and potential banking relationships. The company claimed more than $50 million in financial harm.
The company maintained the transaction was intended to be a Main Street New Loan rather than a Main Street Priority Loan. First Guaranty disputed the alleged mistake and argued The Greenbrier lacked sufficient evidence that the restriction caused its claimed losses.
The bank also pointed to testimony from The Greenbrier President Jillian Justice, the senator’s daughter who admitted she had not read or reviewed the loan documents before signing them, according to the opinion. The Greenbrier relied on the personal knowledge of Vice President Jay Justice, the senator’s son, to support its estimated damages.
The court found it unnecessary to resolve the parties’ competing arguments about mutual mistake. As pleaded, the counterclaim alleged bad faith, but The Greenbrier had not identified a contractual obligation requiring the bank to rescind the addendum.
“That incontestable rule warrants dismissal of Greenbrier’s counterclaim; it has not identified a material contractual obligation requiring FGB to rescind the Note’s Addendum,” the opinion states.
Bank cites separate financing deal
First Guaranty also cited the Kennedy Lewis transaction in challenging The Greenbrier’s contention that the negative pledge prevented it from obtaining financing. Reporting at the time described the arrangement as giving the New York investment firm 51% control of the resort.
The transaction helped resolve separate litigation involving White Sulphur Springs Holdings LLC, which had purchased debt previously held by Carter Bank. The court’s opinion notes that the White Sulphur Springs litigation was dismissed Aug. 14 following the joint venture agreement.
First Guaranty argued The Greenbrier’s ability to complete that transaction undermined its claim that the negative pledge caused its financing problems. The court described that argument but dismissed the counterclaim on the separate ground that The Greenbrier had identified no contractual duty to remove the restriction.
Volk’s November 18 order also denies as moot the bank’s motion to strike what it characterized as The Greenbrier’s untimely fraud claim or defense.
U.S. District Court for the Southern District of West Virginia case number 5:25-cv-00687